Henry Hub futures slid to about $2.51 as warm forecasts trimmed heating demand. Here’s what that means for your heating bill, your power bill, and EQT’s all-stock deal for Range Resources.
By Energy News Beat
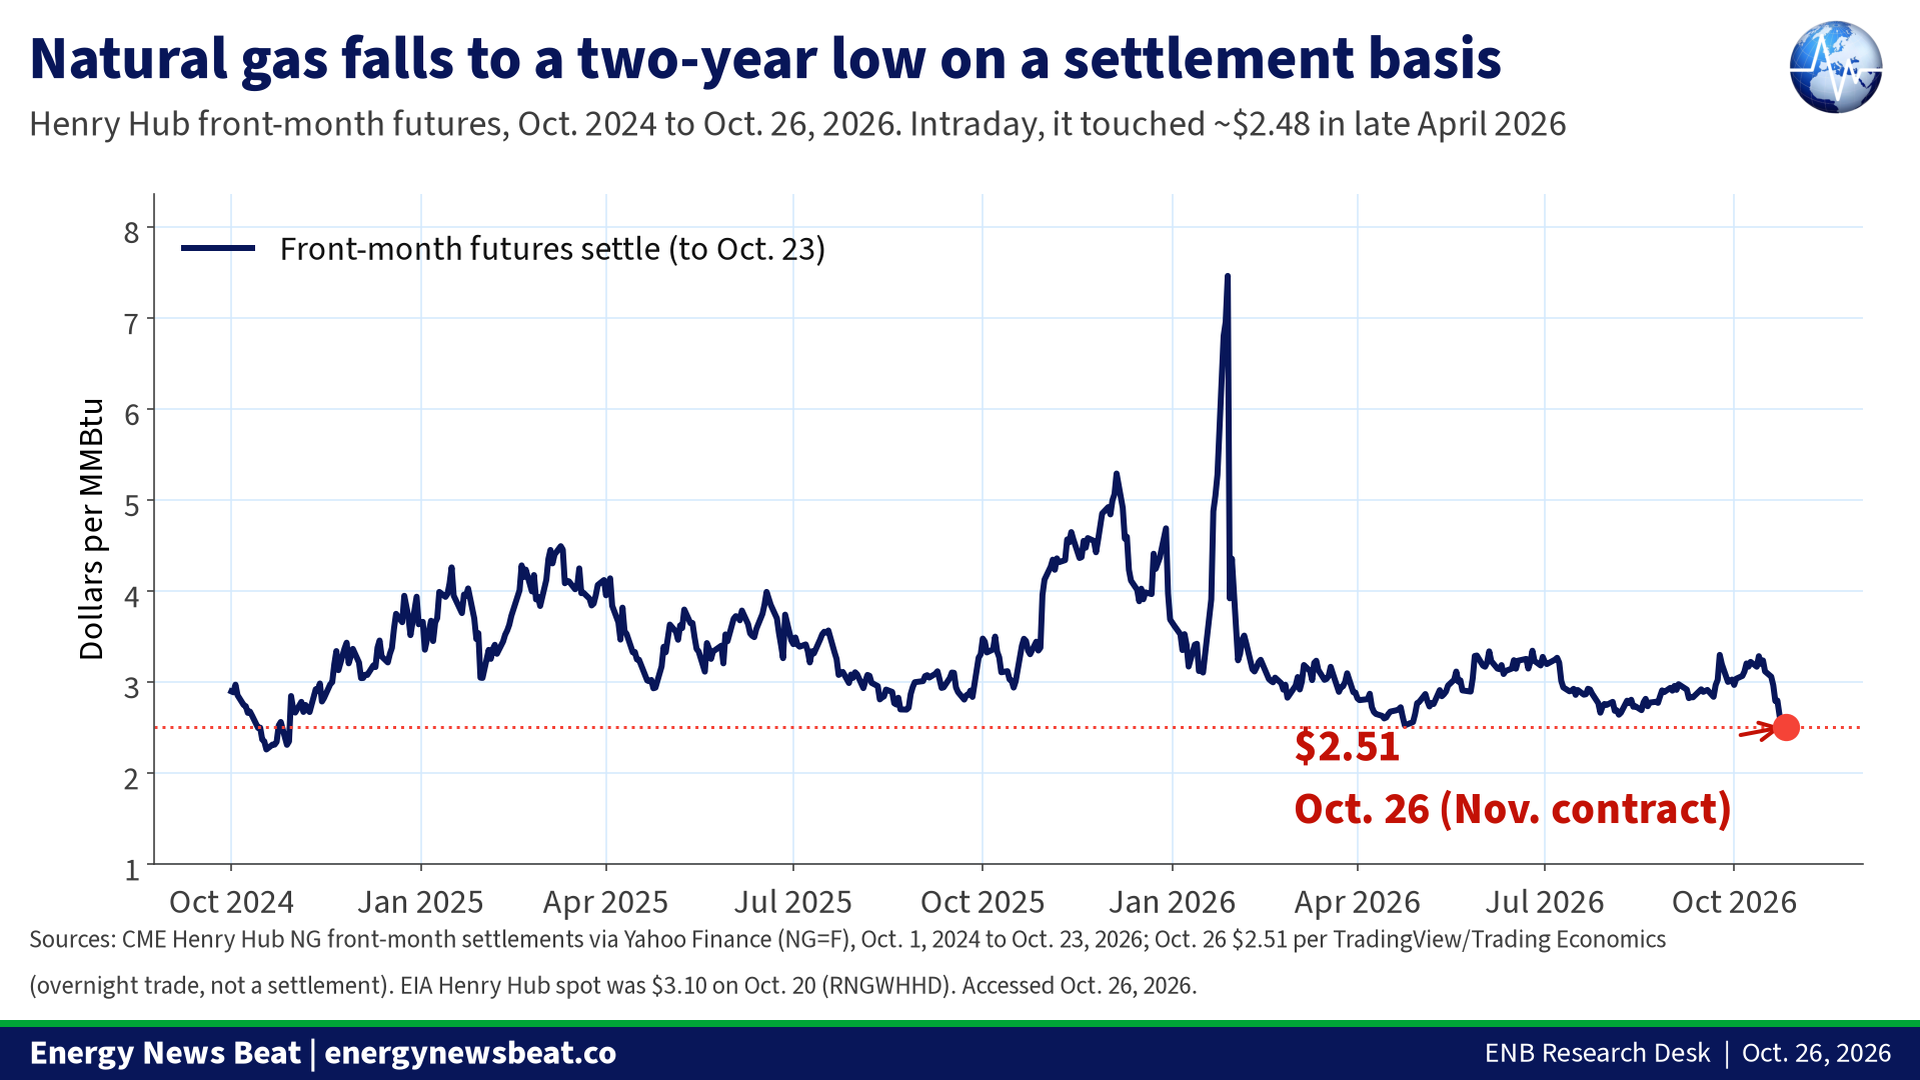
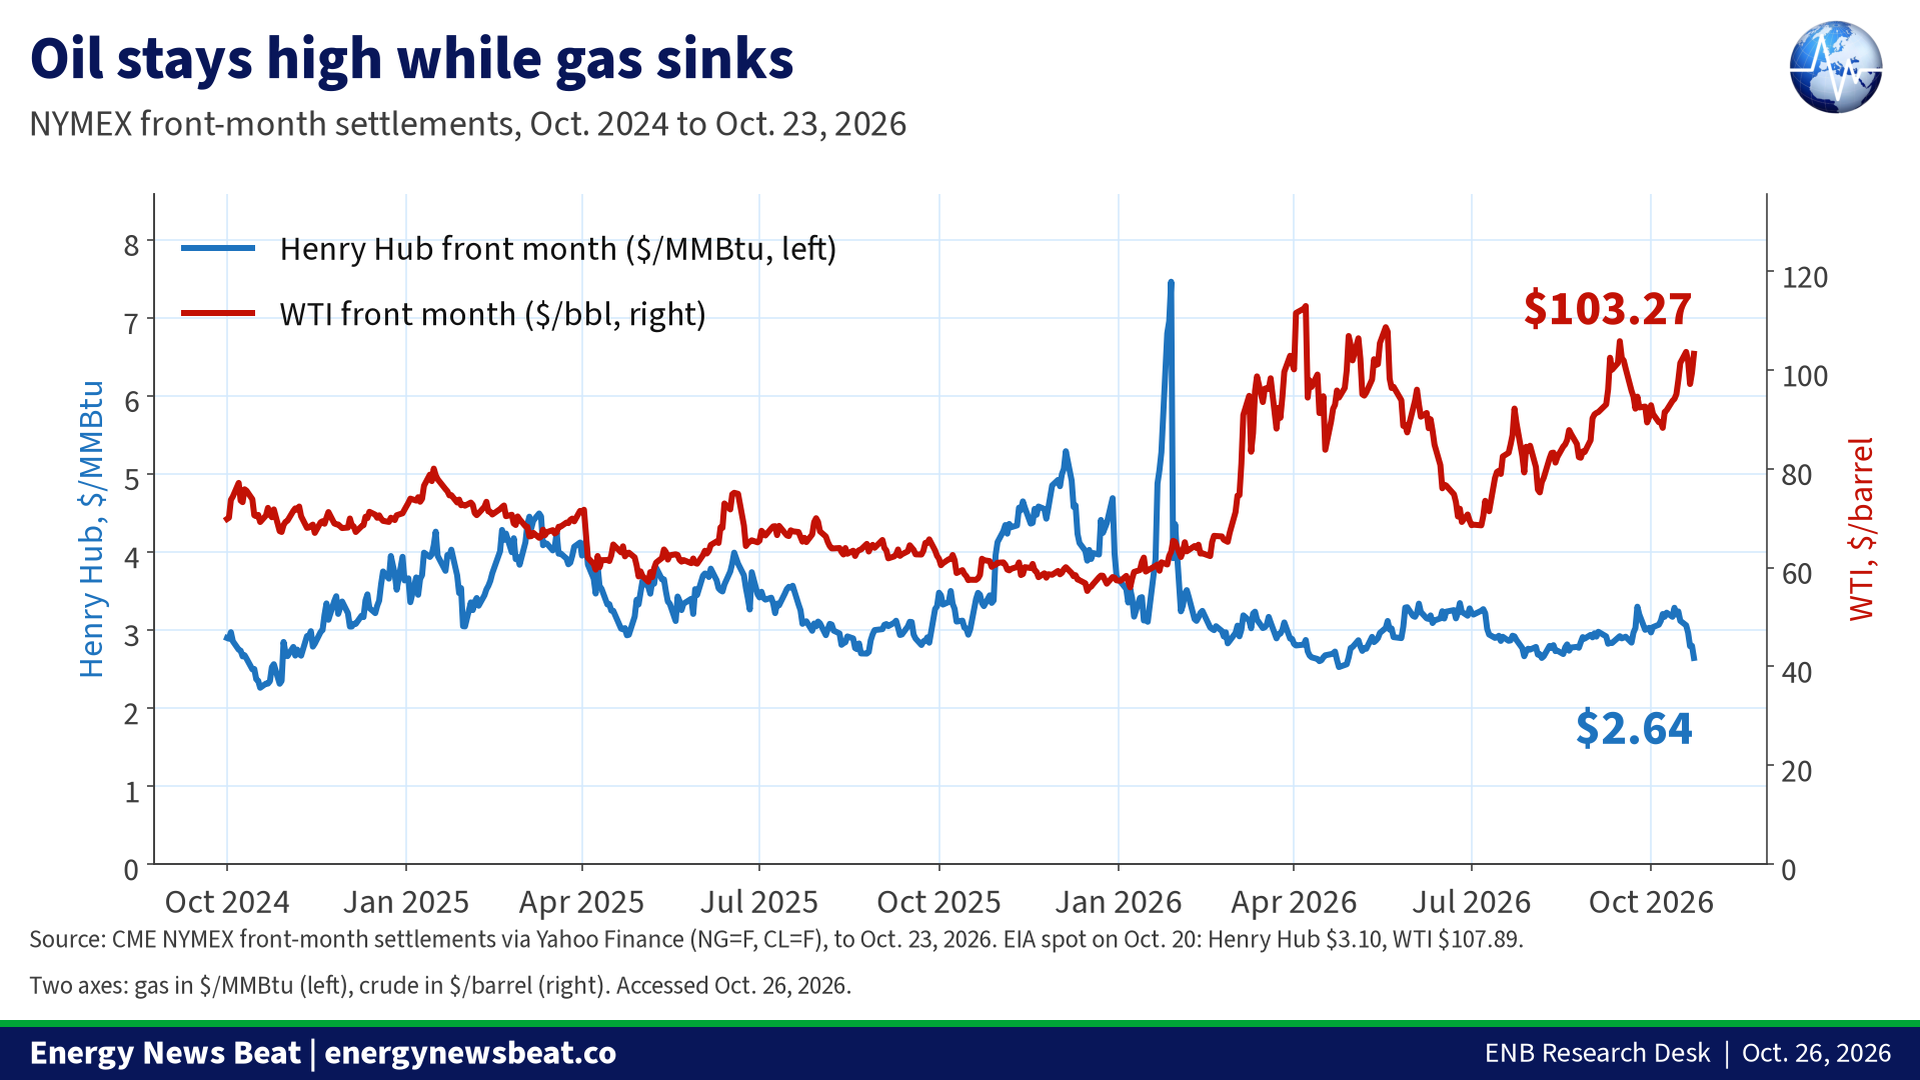
Natural gas fell Monday morning. The front-month Henry Hub futures contract fell more than 4% to about $2.51 per million Btu in early trading ($2.511 at 7:08 AM CT, CME delayed), a level Trading Economics calls the lowest since October 2024, as forecasters called for warmer-than-normal weather across most of the northern two-thirds of the country. On a closing basis, the front month hasn’t settled this low since October 2024. It touched about $2.48 intraday in late April. The November contract closed at $2.640 on Friday and traded as low as $2.50 overnight in delayed CME data.
On the same morning, two of the biggest producers in Appalachia announced they are merging. EQT will buy Range Resources in an all-stock deal. The companies put the combined company’s enterprise value at more than $50 billion. When gas is this cheap, why make a bet this big? And what does cheap gas mean for your household?
Why prices fell
Weather is the main reason. A mild start to heating season means less gas burned in furnaces. Supply is strong too. Lower 48 output averaged about 113.3 Bcf/d over the past week, according to Trading Economics, matching the record monthly averages of August and September reported by LSEG. LSEG data cited by Reuters show flows to the nine big LNG export plants averaged 18.2 Bcf/d so far in October, up from 17.9 in September.
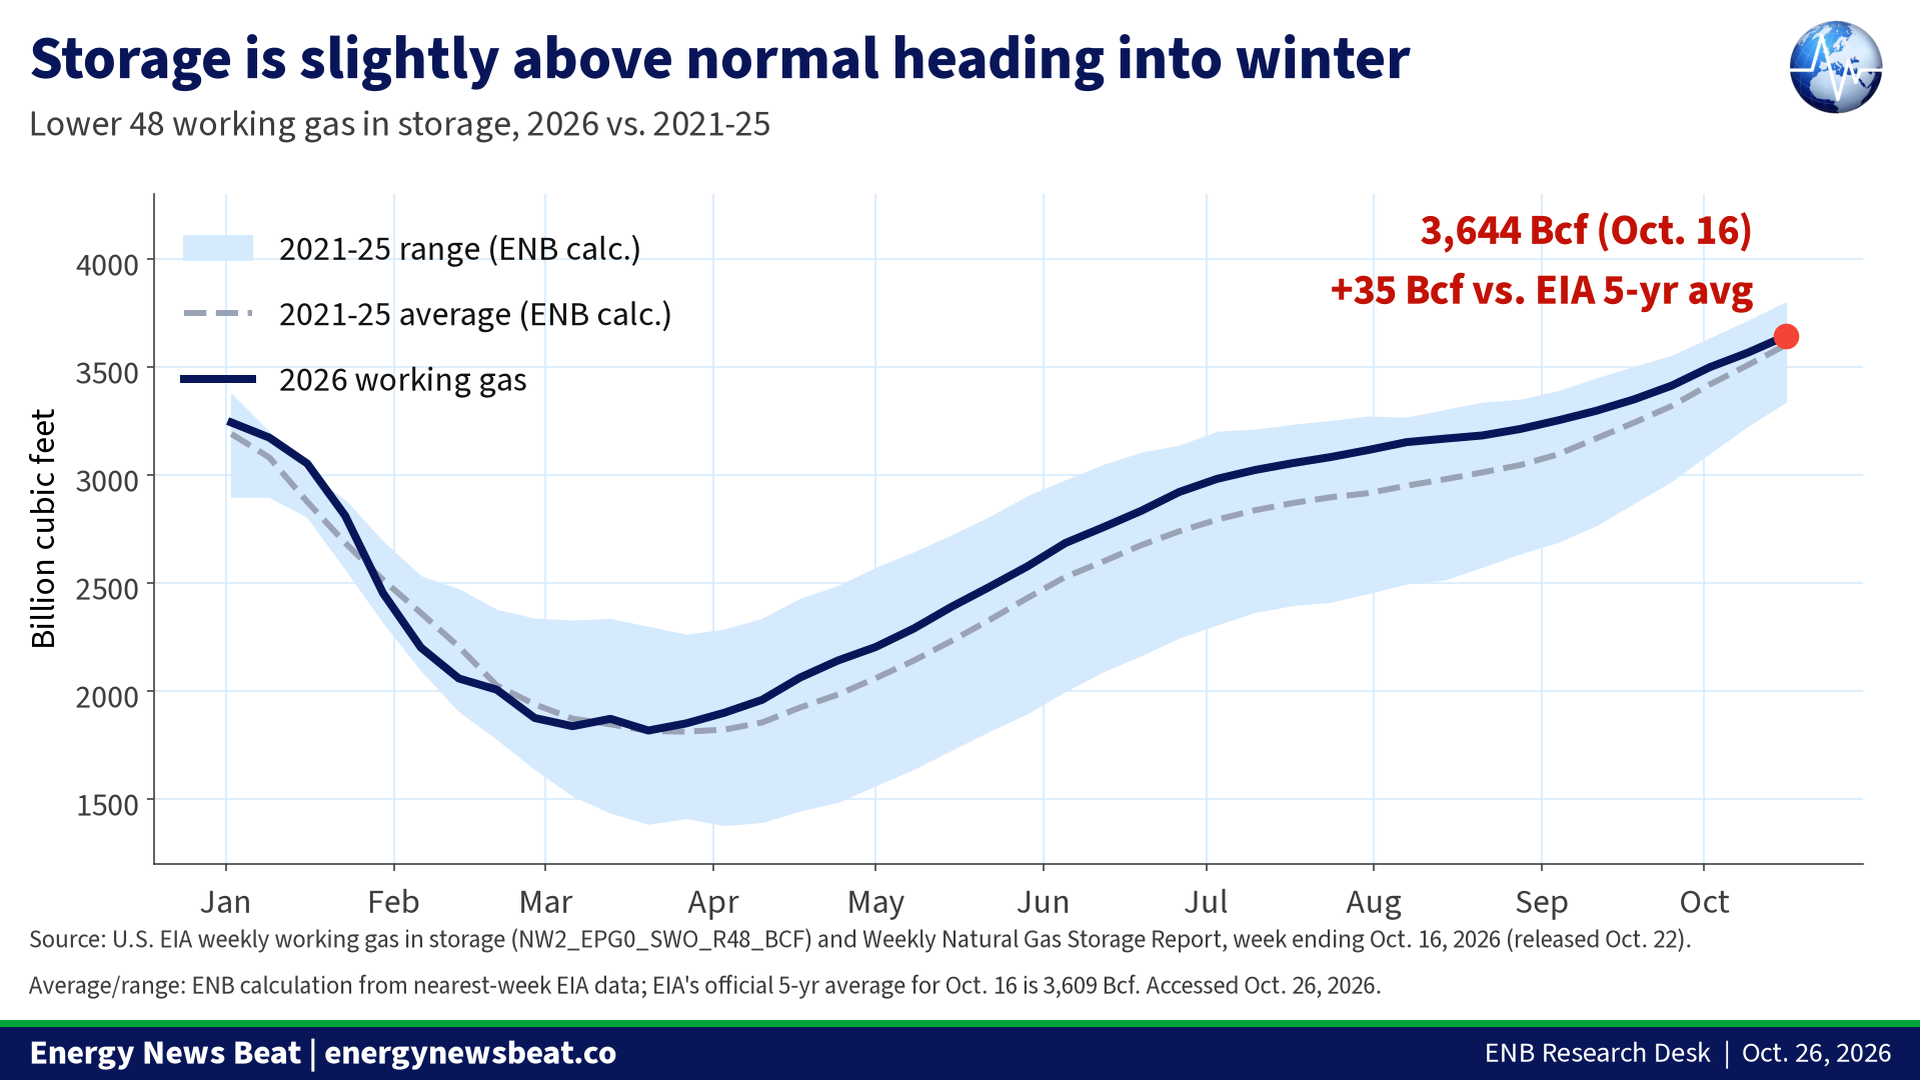
Storage looks comfortable. EIA’s latest weekly report shows 3,644 Bcf of working gas as of Oct. 16. That is 35 Bcf (1.0%) above the five-year average, though 152 Bcf (4.0%) below a year ago.
What it means for your heating bill
Here’s the good news first. EIA’s 2026-27 Winter Fuels Outlook expects homes that heat with natural gas to spend about 9% less this winter than last. That works out to about $640 for November through March, according to CNBC’s report on the outlook. Propane homes are expected to save about 3%.
Now the catch: your bill won’t fall as fast as futures do. Utilities buy gas months ahead, store it, and pass costs through on a regulated schedule. Pipes, meters and service charges make up a big share of a residential bill, and they don’t move with Henry Hub. The latest EIA residential price is $26.45 per thousand cubic feet for July 2026, up from $25.44 a year earlier. Summer prices typically look high because fixed charges are spread over very little gas. Last January the price was $13.96. Expect any relief from today’s drop to show up slowly, over months.
Heating oil households, mostly in the Northeast, get no such break. EIA expects their spending to rise 21%, because tight diesel markets are pushing prices up.
Power bills and data centers
Gas makes about 40% of U.S. electricity, so cheap gas should help power prices over time. It isn’t helping yet. EIA expects homes that heat with electricity to see bills rise about 4% this winter, and it forecasts wholesale PJM power prices up 41% in 2026. Demand is the reason. Reuters notes that growing gas demand from data centers is what pushes producers to chase scale.
The investor angle: who’s betting on cheap gas
EQT is. Under the merger agreement, each Range share converts into 0.987 EQT shares. EQT holders will own about 73% of the company and Range holders about 27%. The companies say the combined company will produce more than 9 Bcfe/d, hold nearly 3 million net acres, more than 30 years of inventory and more than 3,700 miles of midstream pipe. EQT says the deal lowers its unlevered free cash flow breakeven to under $2 per MMBtu, the average Henry Hub price it needs to stay cash-positive.
The companies also expect $325 million a year in base synergies within two years, with a path to more than $600 million longer term. Reuters calculates an implied price of $54.91 per Range share, about 20.6% above Friday’s close, or about $12.83 billion in equity. Premarket, EQT fell 4.6% and Range rose 10.1%. The deal needs shareholder and antitrust approval. It is expected to close in the first quarter of 2027, and the termination fees are $423 million (Range) or $1.148 billion (EQT).
| Stu’s Take
Gas futures near $2.51 this morning while WTI spot was $107.89 last week is a split you don’t see often. EQT just put its name on a combined company valued at more than $50 billion with a sub-$2 breakeven, buying when the price is low. EQT is betting that today’s low won’t last, and that is the bet behind this merger. For families on gas heat, EIA’s 9% lower winter estimate is real relief, but it reaches your bill slowly. For anyone on electric heat, it’s 4% higher. Storage is 35 Bcf above the five-year average. One cold snap can change that fast. |
Caveats, to be fair
- The $2.51 figure is the expiring November futures contract in overnight trade, not a final settlement. With the December contract near $2.99 (7:09 AM CT) and the EIA spot price was $3.10 on Oct. 20, today’s level is not a settled price. November expires this week.
- “Over $50 billion” is the combined company’s pro forma enterprise value, per the companies. It is not the price paid for Range. The equity value is about $12.83 billion, a Reuters calculation.
- The past-week output figure (113.3 Bcf/d) comes from Trading Economics only. The record monthly averages and the LNG feedgas figures come from LSEG data cited by Reuters. EIA’s own numbers lag, and ENB could not match them to an EIA release.
- Breakeven, synergies and free cash flow figures are company projections, and the breakeven is a non-GAAP measure. The deal can still fail at the shareholder or antitrust stage.
- Winter outlooks assume normal weather. EIA flags a strong El Niño as a wild card. Your bill depends on your utility, your state regulator and your thermostat.
Appendix
- Sources (all accessed Oct. 26, 2026)
- TradingView / Trading Economics: US Natural Gas Sinks to Two-Year Low (published Oct. 25, 2026, 11:17 PM CT)
- Reuters via StreetInsider: EQT, Range tie up in $50 billion-plus deal (Oct. 26, 2026)
- Reuters via Investing.com (same story, updated 6:36 AM CT)
- Range Resources press releases page: joint EQT-Range release, Oct. 26, 2026
- SEC EDGAR: EQT Form 8-K (filed Oct. 26, 2026), merger terms
- SEC EDGAR: Exhibit 99.1, joint EQT-Range press release (Oct. 26, 2026)
- Business Recorder (Reuters, Oct. 22, 2026): LSEG output and LNG feedgas data
- Range Resources Form 8-K (filed Oct. 26, 2026)
- SEC EDGAR: EQT filings index
- CME Group Henry Hub natural gas futures
- Yahoo Finance NGX26.NYM (November 2026 NG futures, CME delayed)
- Yahoo Finance NGZ26.NYM (December 2026 NG futures, CME delayed)
- EIA Henry Hub daily spot price (RNGWHHD)
- EIA WTI Cushing daily spot price (RWTC)
- EIA Weekly Natural Gas Storage Report, week ending Oct. 16, 2026 (released Oct. 22)
- EIA weekly Lower 48 working gas in storage series
- EIA U.S. residential natural gas price, monthly (N3010US3)
- EIA press release, Oct. 6, 2026: Winter Fuels Outlook and October STEO
- EIA Today in Energy, Oct. 7, 2026: Mixed outlook for energy expenditures this winter
- CNBC, Oct. 7, 2026: Heating oil costs are surging (Winter Fuels Outlook dollar figures)
- EIA Short-Term Energy Outlook
- Key excerpts
- TradingView/Trading Economics: “US natural gas prices plunged more than 4% to $2.51 per MMBtu, their lowest level since October 2024, as warm weather forecasts dampened expectations for near-term heating demand.” … “output across the US Lower 48 states averaging around 113.3 bcfd over the past week” … “gas flows to the nine major LNG export terminals rose to 18.2 bcfd so far in October.”
- Reuters via Business Recorder (Oct. 22), citing LSEG: Lower 48 output hit records of 113.3 bcfd in August and September (111.5 so far in October), and LNG feedgas averaged “18.2 bcfd so far in October, up from 17.9 bcfd in September.”
- EQT Form 8-K, Item 1.01: each Range share “will be converted into the right to receive, without interest, 0.987 (the “Exchange Ratio”) shares of common stock … of EQT.” EQT and Range holders will own “approximately 73% and 27%, respectively … on a fully diluted basis.”
- Joint release (Exhibit 99.1): “pro forma enterprise value over $50 billion” … “>9 Bcfe/d of net production and >30 years of inventory across nearly 3 million net acres in addition to >3,700 miles of critical midstream infrastructure” … “Improves EQT’s unlevered free cash flow breakeven to less than $2 per MMBtu” … “$325 million of base annual synergies within two years … pathway to more than $600 million long-term.” Expected close: “during the first quarter of 2027.”
- Reuters: “The implied offer price of $54.91 per share is about 20.6% above Range Resources’ last closing price on Friday. Shares of EQT were down 4.6% in premarket trading, while those of Range Resources were up 10.1%.”
- EIA storage report: “Working gas in storage was 3,644 Bcf as of Friday, October 16, 2026 … Stocks were 152 Bcf less than last year at this time and 35 Bcf above the five-year average of 3,609 Bcf.”
- EIA Today in Energy (Oct. 7): “We expect energy expenditures will decrease on average by 9% in homes heating with natural gas” … “more than 40% of homes heating with electricity will experience a 4% increase in electricity bills on average.” CNBC: “Homes primarily heated with natural gas are expected to spend an average of $640 this winter, down 9%.”
- EIA press release (Oct. 6): “EIA forecasts the Henry Hub spot price will average $3.16 per million British thermal units (MMBtu) in 2027, down 9% from 2026.” … “wholesale PJM prices rise 41%.”
- Data tables
| Measure | Value | As of | Source |
| NG Nov. 2026 futures, overnight low/print | $2.50 low; ~$2.51 reported; $2.552 at 7:00 AM CT | Oct. 26, 2026 | Yahoo (CME delayed); TradingView |
| NG Nov. 2026 futures settle | $2.640 | Oct. 23, 2026 | Yahoo (CME delayed) |
| NG Dec. 2026 futures | $2.986 | Oct. 26, 2026, 7:09 AM CT | Yahoo (CME delayed) |
| Lowest front-month settle, Nov. 2024 to Oct. 23, 2026 | $2.523 (Apr. 24, 2026) | – | Yahoo NG=F |
| Last front-month settle below $2.51 | $2.309 | Oct. 28, 2024 | Yahoo NG=F |
| EIA Henry Hub spot | $3.10/MMBtu | Oct. 20, 2026 | EIA RNGWHHD |
| EIA WTI spot | $107.89/bbl | Oct. 20, 2026 | EIA RWTC |
| WTI front-month settle | $103.27/bbl | Oct. 23, 2026 | Yahoo CL=F |
| Working gas, Lower 48 | 3,644 Bcf (+77 w/w) | Week ending Oct. 16, 2026 | EIA WNGSR |
| vs. five-year avg (3,609) | +35 Bcf (+1.0%) | Oct. 16, 2026 | EIA WNGSR |
| vs. year ago (3,796) | -152 Bcf (-4.0%) | Oct. 16, 2026 | EIA WNGSR |
| U.S. residential gas price | $26.45/Mcf (July 2025: $25.44; Jan. 2026: $13.96) | July 2026 (latest) | EIA N3010US3 |
| Gas-heat winter spending | ~$640, -9% | Nov. 2026-Mar. 2027 forecast | EIA WFO via CNBC; EIA TIE |
| Electric-heat winter bills | +4% | Forecast | EIA TIE |
| Henry Hub forecast | $3.48 (2026), $3.16 (2027) | Oct. 2026 STEO | EIA |
Front-month futures figures come from Yahoo Finance’s delayed CME data. They are not CME official settlement files. ENB could not load CME’s settlement page directly.
| Deal term | Value | Status | Source |
| Structure | All-stock; EQT acquires Range | Verified | 8-K, release |
| Exchange ratio | 0.987 EQT per Range share | Verified | 8-K Item 1.01 |
| Ownership | 73% EQT / 27% Range | Verified | 8-K |
| Size | Pro forma EV >$50B (combined company) | Verified, with a wording caveat | Release |
| Equity value / implied price | ~$12.83B / $54.91 per share | Reuters calculation | Reuters |
| Premium | ~20.6% vs. Friday close | Reuters calculation | Reuters |
| Production | >9 Bcfe/d net | Verified (company) | Release |
| Acreage | Nearly 3M net acres | Verified (company) | Release |
| Midstream | >3,700 miles | Verified (company) | Release |
| Breakeven | Unlevered FCF breakeven <$2/MMBtu (non-GAAP) | Verified (company projection) | Release |
| Synergies | $325M/yr base within 2 yrs; >$600M long-term | Verified (company projection) | Release |
| Close | Q1 2027; outside date Oct. 25, 2027 (extendable to Apr. 25, 2028) | Verified | 8-K |
| Termination fees | $423M (Range) / $1.148B (EQT) | Verified | 8-K |
| Premarket moves | EQT -4.6%, RRC +10.1% | Reuters only | Reuters |
- Methodology
- Each claim in the brief was checked against the closest primary record. For prices that meant EIA series and CME futures (delayed, via Yahoo Finance). For deal terms it meant the EQT and Range Form 8-Ks and the joint release filed as Exhibit 99.1. For winter costs it meant EIA’s Oct. 6 press release and Oct. 7 Today in Energy. Reuters was used for its own calculations (implied price, premium, equity value) and for premarket moves.
- Two-year low test: in the front-month continuous series, the lowest settlement from Nov. 1, 2024 to Oct. 23, 2026 was $2.523 (Apr. 24, 2026). The last settlement below $2.51 was Oct. 28, 2024 ($2.309). A $2.51 level is therefore the lowest since October 2024 on a settlement basis only. Intraday, the front month traded down to $2.483 on Apr. 27, 2026, so on an intraday basis Oct. 26 is a six-month low. The article says this. The EIA spot series bottomed at $2.54 in April 2026 and was $3.10 on Oct. 20.
- Percent drop: $2.51 vs. the $2.640 Friday settle is -4.9%, consistent with ‘more than 4%.’
- Storage chart: the 2021-25 average and range are ENB calculations that match each 2026 week to the nearest-date week in each prior year. The result for Oct. 16 is 3,602 Bcf, against EIA’s official 3,609 Bcf. The article text uses EIA’s official figure.
- Bill lag: the residential price comparison uses EIA’s monthly series, whose latest month is July 2026. Summer residential prices per Mcf are seasonally high because fixed charges are spread over low volumes.
- The WFO dollar figure ($640) was taken from CNBC’s report on the outlook, because EIA’s Winter Fuels page returned a server error when accessed. The -9% figure is confirmed on EIA’s own Today in Energy page.
- Attribution: the 113.3 Bcf/d past-week output figure comes from Trading Economics only. The 113.3 Bcf/d August/September records and the 18.2 Bcf/d October LNG feedgas (17.9 in September) are LSEG data cited by Reuters (Business Recorder, Oct. 22). Not independently verified, the premarket share moves (Reuters only), and the exact $2.51 print (the delayed CME data showed a $2.50 low).