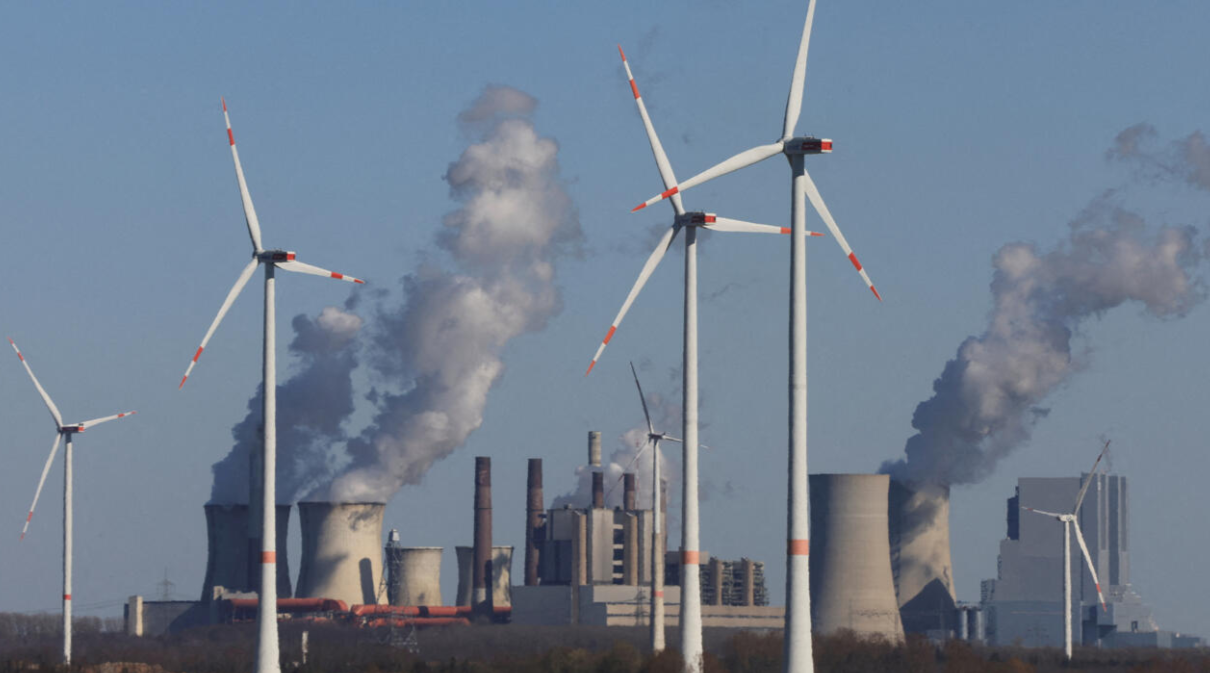
Europe spent a decade congratulating itself for pushing coal to the edge of the power system. Then it priced itself back onto the fuel it spent political capital destroying.
Benchmark Dutch TTF gas prices spiked above €80 per megawatt-hour this month, the highest in three years, after the Iran conflict choked LNG shipments through the Strait of Hormuz. That flipped the economics of European power. Coal and lignite plants are more profitable to run, on average, than gas plants for the first time since at least 2024. Analysts now expect European coal-fired generation to jump about 27 percent in the fourth quarter as gas-fired output falls.
The uncomfortable part is not the price spike. Price spikes happen. The uncomfortable part is how little firm capacity Europe left itself after years of plant closures, nuclear shutdowns, and premature demolitions. When gas gets expensive, the remaining coal fleet is already close to its practical limit.france24.com
The EU mix: cleaner on paper, tighter in practice
The 2025 numbers look like a transition success story if you stop at the headline.
Wind and solar generated 30 percent of EU electricity in 2025, edging past all fossil fuels at 29 percent for the first time. Renewables as a group supplied about 47–48 percent. Nuclear contributed roughly 23 percent. Coal fell to a record low of 9.2 percent. In 19 of 27 EU countries, coal is now under 5 percent of generation.
That is real progress. It is also incomplete.
Gas generation still rose 8 percent in 2025 because hydro dropped 12 percent and wind slipped 2 percent. The EU power sector’s gas import bill jumped to €32 billion, up 16 percent. Price spikes in the hours when gas plants had to run lifted wholesale power prices in 21 EU countries. Wind and solar can crowd fossils out of the annual average. They cannot replace dispatchable plants on a dark, still winter evening.
Eurostat’s preliminary 2025 picture is the same story in official clothing: renewables 47.2 percent of electricity, fossils 29.6 percent, nuclear 23.2 percent. Fossil generation rose 3.2 percent even as coal supply kept falling, because gas filled the weather gap.
Coal’s annual share can fall while coal still becomes the winter backstop. That is the situation Europe is in now.
Who is going back to coal?
Germany is the center of the problem because it is Europe’s largest power market and largest gas consumer.
Coal still supplied about 21–22 percent of German electricity in 2025. Renewables were near 59 percent. Fossils as a group were still about 41 percent. Germany closed its last nuclear plants in 2023 and now has less flexibility when wind and solar drop. Veyt’s data show German coal-fired generation heading toward its practical quarterly limit this winter. Almost all remaining spare coal capacity is constrained by plant availability, not by economics. “Even if the price of gas reaches €100/MWh, the power sector could not react that much more,” ICIS analyst Florian Boehnke told Reuters.
Chancellor Friedrich Merz has said the quiet part out loud: if the energy crisis persists, Germany may have to keep coal plants online longer than planned. “We have to supply this country with electricity. I am not prepared to jeopardize the core of our industry simply because we have adopted phase-out plans that have become unrealistic.” Germany’s official coal exit remains 2038, with an earlier 2030 lignite target in North Rhine-Westphalia that officials can review. Replacement gas plants are late. The market is already using the coal that is left.
Italy went further. Rome had pledged to exit coal by the end of 2025. In 2026, it moved the deadline to 2038. Energy Minister Gilberto Pichetto Fratin said plants such as Brindisi and Civitavecchia could be reactivated if gas stayed above about €70/MWh. Italy still has on the order of 4.6–4.7 GW of coal capacity, some of it mothballed rather than demolished. That is a policy reversal dressed up as emergency planning.
Poland never left. Ember puts coal at 51 percent of Polish electricity in 2025 — a record low for Warsaw, and still the highest share in the EU. Other tallies for domestic generation put hard coal plus lignite closer to the mid-50s or even around 60 percent depending on the dataset. Poland has no EU-style early exit date. When gas is expensive, and wind is weak, Polish coal is not a “return.” It is the system.
Veyt analyst Marta Wroniszewska has said coal is expected to remain cheaper than gas for European power generation through next year and potentially until March 2028 if supply constraints persist. Europe can lean on coal for two winters. After that, the constraint is physical plant, not ideology.
Germany and the UK blew theirs up
This is the part that will look reckless in hindsight.
The UK shut Ratcliffe-on-Soar, its last coal-fired station, on September 30, 2024, ending more than 140 years of coal generation. Demolition approval followed. Uniper hired contractors. Cooling towers and the main plant are scheduled to come down with explosives, with the towers not expected before 2029 and site clearance running into 2030–2031. Britain is now a coal-free power system by statute and by wrecking ball. That is a climate milestone. It is also a reliability choice that cannot be reversed in a winter.
Germany is doing the same thing on a rolling basis. RWE demolished the 90-meter boiler house of the 695 MW Voerde Unit B with explosives on August 21, 2026. The Ibbenbüren boiler house and cooling tower were brought down earlier. These plants closed because carbon costs and politics made them uneconomic — until gas prices made the remaining fleet valuable again. Germany is simultaneously tendering new firm capacity for Dunkelflaute periods and knocking down the firm capacity it already owned. RWE wants a hydrogen-ready gas plant at Voerde around 2030. That is a six-year gap dressed up as a transition.
Closing dirty plants is not automatically bad policy. Closing them before replacement dispatchable capacity exists, while remaining dependent on imported LNG, is.
Japan is running coal harder
Japan did not pretend gas would always be cheap.METI suspended, for fiscal 2026, the rule that kept less-efficient coal plants at or below a 50 percent operating rate. Those plants can also enter capacity-market auctions they had been pushed out of for climate reasons. Officials said the one-year change was meant to save LNG after Hormuz risk hit Japanese imports. Estimates put the LNG saving around 0.5 million tonnes a year. Bloomberg data later showed Japan’s 30-day coal generation running about 17 percent above the prior year, with gas down about 10 percent. Rystad has pointed to Japan leading an Asian coal-burn increase as LNG tightened.
Tokyo still talks about long-term decarbonization. In the meantime, it is using the coal fleet it kept.
The United States increased coal in 2025 — and is trying to keep the plants
The U.S. story is not a European-style scramble. It is demand plus policy.
Rhodium Group estimated U.S. greenhouse-gas emissions rose 2.4 percent in 2025 after two years of decline, with utilities burning about 13 percent more coal than in 2024. Electricity demand grew as data centers, manufacturing, and EVs added load. Higher gas prices made existing coal plants competitive again. The Energy Department ordered multiple coal units to stay open past planned retirement dates. Global Energy Monitor noted the U.S. was the only major economy to increase coal generation in 2025 under a policy shift that slowed clean-energy deployment and delayed retirements.
EIA’s latest short-term outlook is less bullish for 2026–2027. It sees coal generation falling 8 percent in 2026 and 6 percent in 2027 as solar and gas grow, with coal’s generation share sliding from 17 percent in 2025 to 16 percent in 2026 and 14 percent in 2027. That forecast can coexist with a political project to keep coal plants available. Generation can fall while capacity is prevented from disappearing. That is the U.S. version of the same reliability argument Europe is now making after it already retired the plants.
China never left
China is not “going back” to coal. It never left, and it is still building.
Global Energy Monitor and CREA found China commissioned about 78 GW of new coal plants in 2025, the highest annual total in a decade, and logged a record 161.7 GW of new or reactivated proposals. The operating fleet is above 1,200 GW. Roughly 270–290 GW remains in the pipeline. Coal generation did fall about 1–2 percent in 2025 as wind and solar met incremental demand — then rebounded in the first half of 2026 as weather, demand, and gas prices shifted. Solar has overtaken coal in installed capacity. Coal still does the heavy lifting when the system needs firm power. Utilization is falling. The plants are still being built.
Europe debates whether a 695 MW boiler house should have been demolished. China adds more coal in a year than some countries have in their entire fleet.
The policy lesson is not complicated
High gas prices did not invent coal’s usefulness. They exposed a design flaw.
Europe cut coal from more than a third of EU electricity in 1990 to 9.2 percent in 2025. It shut nuclear in Germany. It demolished coal plants in Germany and the UK. It built a remarkable amount of wind and solar. It did not build enough firm, affordable replacement capacity. When LNG routes tightened, clean dark spreads beat clean spark spreads, carbon prices rose with the extra coal burn, and governments in Italy and Germany started rewriting phase-out calendars.
Japan kept the option and used it. The United States used more coal in 2025 and delayed retirements. China kept building. Europe spent years making the option smaller, then discovered it still needed it.
Coal is not the future of European power. An energy system that retires the backup before the backup exists is not a climate strategy. It is a bet that the weather and the Strait of Hormuz will cooperate. This winter, they are not.
Making Appendices Great Again
Check out the World’s Greatest Podcast Show Notes at EnergyNewsBeat.co or EnergyNewsBeat.com.
Appendix: Sources and links
- Reuters, “High European gas prices push power producers back to coal,” Sept. 24, 2026. https://www.reuters.com/business/energy/high-european-gas-prices-push-power-producers-back-coal-2026-09-24/
- Bloomberg / Washington Post syndication, “EU carbon rises to highest since January as coal use ramps up,” Sept. 14, 2026. https://www.bloomberg.com/news/articles/2026-09-14/eu-carbon-rises-to-highest-since-january-as-coal-use-ramps-up
- Carbon Pulse, “EU coal power generation increases 45% YoY in August,” Sept. 21, 2026. https://carbon-pulse.com/552183/
- IEA, Coal Mid-Year Update 2026. https://www.iea.org/reports/coal-mid-year-update-2026/overview
- IEA news, “Global coal demand set to increase this year amid Middle East conflict,” Sept. 10, 2026. https://www.iea.org/news/global-coal-demand-set-to-increase-this-year-amid-middle-east-conflict
- S&P Global, “European thermal coal imports may rise as Middle East war jolts gas supply outlook.” https://www.spglobal.com/energy/en/news-research/latest-news/coal/032026-european-thermal-coal-imports-may-rise-as-middle-east-war-jolts-gas-supply-outlook
- Trading Economics, EU Natural Gas (TTF). https://tradingeconomics.com/commodity/eu-natural-gas
- OilPriceAPI / live TTF feed. https://www.oilpriceapi.com/live/dutch-ttf-gas-price
- European Gas Hub, “TTF gas prices combine with lower wind output to lift European power prices,” Sept. 16, 2026. https://europeangashub.com/report-presentation/ttf-gas-prices-combine-with-lower-wind-output-to-lift-european-power-prices/
EU electricity mix
- Ember, European Electricity Review 2026. https://ember-energy.org/latest-insights/european-electricity-review-2026/
- Ember, “Wind and solar generated more power than fossil fuels in the EU for the first time in 2025.” https://ember-energy.org/latest-updates/wind-and-solar-generated-more-power-than-fossil-fuels-in-the-eu-for-the-first-time-in-2025/
- Reuters, “Wind and solar beat fossil fuels in EU power mix in 2025,” Jan. 21, 2026. https://www.reuters.com/sustainability/climate-energy/wind-solar-beat-fossil-fuels-eu-power-mix-2025-energy-think-tank-says-2026-01-21/
- Eurostat, “Renewable energy and natural gas supply up in 2025,” June 29, 2026. https://ec.europa.eu/eurostat/web/products-eurostat-news/w/ddn-20260629-2
- Eurostat, “54% of EU’s electricity came from renewables in Q2 2026,” Sept. 18, 2026. https://ec.europa.eu/eurostat/web/products-eurostat-news/w/ddn-20260918-1
- Eurostat Statistics Explained PDF, energy production and imports. https://ec.europa.eu/eurostat/statistics-explained/SEPDF/cache/1216.pdf
- IEA, Electricity Mid-Year Update 2026 PDF. https://iea.blob.core.windows.net/assets/3c66a000-244c-4efb-aaeb-cda33eb833da/ElectricityMid-YearUpdate2026.pdf
Germany
- Ember Germany country page. https://ember-energy.org/countries-and-regions/germany/
- Bundesnetzagentur, 2025 electricity market data. http://www.bundesnetzagentur.de/SharedDocs/Pressemitteilungen/EN/2026/20260104_SMARD.html
- BDEW, Bundesdeutscher Strommix 2025. https://www.bdew.de/media/documents/260413_Bundesdeutscher_Strommix_2025.pdf
- Enerdata, “Renewables covered 58.6% of Germany’s power mix in 2025.” https://www.enerdata.net/publications/daily-energy-news/renewables-covered-586-germanys-power-mix-2025.html
- Reuters, “Could Germany run some of its coal-fired power plants longer?” Aug. 14, 2026. https://www.reuters.com/business/energy/could-germany-run-some-its-coal-fired-power-plants-longer-2026-08-14/
- The Local/AFP, “Energy crisis may force Germany to run coal plants longer,” March 28, 2026. https://www.thelocal.de/20260328/energy-crisis-may-force-germany-to-run-coal-plants-longer
- BBC, “Is Germany looking again at coal-powered electricity?” https://www.bbc.co.uk/news/articles/cy04ykxrj5eo
- Clean Energy Wire, “Driven by markets, Germany’s coal exit remains on track amid energy crisis.” https://www.cleanenergywire.org/news/driven-markets-germanys-coal-exit-remains-track-amid-energy-crisis
- Blackout News, “Voerde Coal-Fired Power Plant: RWE Demolishes Boiler House of 695 MW Unit,” Sept. 1, 2026. https://blackout-news.de/en/energy/voerde-coal-fired-power-plant-rwe-demolishes-boiler-house-of-695-mw-unit/
- Sky News, coal plant demolition in Ibbenbüren. https://news.sky.com/video/coal-fired-power-plant-demolished-in-germany-in-move-to-green-energy-13343333
Italy and Poland
- Reuters, “Italy to postpone shutdown of coal-powered plants by 13 years,” March 31, 2026. https://www.reuters.com/sustainability/climate-energy/italy-postpone-shutdown-coal-powered-plants-by-13-years-2026-03-31/
- Enerdata, “Italy plans to delay coal power phase out to 2038.” https://www.enerdata.net/publications/daily-energy-news/italy-plans-delay-coal-power-phase-out-2038.html
- The Telegraph, “Italy prepares to keep coal power stations open for another decade,” March 31, 2026. https://www.telegraph.co.uk/business/2026/03/31/italy-to-keep-coal-power-stations-open-for-another-decade/
- IEA policy page, Energy Decree 2026 coal decommissioning. https://www.iea.org/policies/31120-energy-decree-2026-decommissioning-of-coal-fired-power-plants
- Ember Poland country page. https://ember-energy.org/countries-and-regions/poland/
- Notes From Poland, “Share of renewables in Poland’s energy mix stagnant in 2025, with coal still dominant.” https://notesfrompoland.com/2026/01/02/share-of-renewables-in-polands-energy-mix-stagnant-in-2025-with-coal-still-dominant/
- energy.instrat, Coal Brief December 2025. https://energy.instrat.pl/en/coal-brief-december-2025-and-yearly-summary/
- Carbon Brief, “World ‘will not see significant return to coal’ in 2026 – despite Iran crisis.” https://www.carbonbrief.org/world-will-not-see-significant-return-to-coal-in-2026-despite-iran-crisis
United Kingdom plant closures and demolition
- Uniper, “The end of an era – Ratcliffe-on-Soar power station ends coal generation.” https://www.uniper.energy/united-kingdom/news/the-end-of-an-era—ratcliffe-on-soar-power-station-ends-coal-generation/
- Uniper plant page, Ratcliffe-on-Soar. https://www.uniper.energy/united-kingdom/power-plants-united-kingdom/ratcliffe-soar
- BBC, “Demolition of UK’s last coal-fired power station approved,” Oct. 3, 2025. https://www.bbc.co.uk/news/articles/cvgqez9gqrko
- Nottingham Post, demolition milestone, Oct. 3, 2025. https://www.nottinghampost.com/news/key-milestone-reached-major-plans-10549136
- Construction News, “Erith lands Nottinghamshire power station demolition job,” June 5, 2026. https://www.constructionnews.co.uk/civils/erith-lands-nottinghamshire-power-station-demolition-job-05-06-2026/
- MIT Technology Review, “The UK is done with coal. How’s the rest of the world doing?” Sept. 30, 2024. https://www.technologyreview.com/2024/09/30/1104591/uk-coal-global-shutdown/
Japan
- Reuters, “Japan to relax rules from April to boost coal-fired power amid LNG import risks,” March 27, 2026. https://www.reuters.com/business/energy/japan-considers-increasing-coal-fired-power-war-disrupts-lng-imports-2026-03-27/
- The Japan Times, “Japan to allow more coal-fired power to cope with energy shock.” https://www.japantimes.co.jp/business/2026/03/27/coal-power-plants-energy/
- Nippon.com / Jiji, “Japan to Raise Coal-Fired Power Plant Operating Rate.” https://www.nippon.com/en/news/yjj2026032701021/
- Bloomberg, “Japan’s Coal Power Generation Climbs as War Makes LNG Expensive,” May 13, 2026. https://www.bloomberg.com/news/articles/2026-05-13/japan-s-coal-power-generation-climbs-as-war-makes-lng-expensive
- OilPrice.com / Rystad, “Asia’s Coal Demand to Jump 70 Million Tonnes in 2026 as LNG Shortfall Bites.” https://oilprice.com/Energy/Energy-General/Asias-Coal-Demand-to-Jump-70-Million-Tonnes-in-2026-as-LNG-Shortfall-Bites.html
- Kiko Network / OCCTO supply plan note. https://beyond-coal.jp/en/news/occto-electricity-supply-plan2026/
United States
- New York Times, “U.S. Emissions Jumped in 2025 as Coal Power Rebounded,” Jan. 13, 2026. https://www.nytimes.com/2026/01/13/climate/us-emissions-2025-coal-power.html
- EIA Short-Term Energy Outlook, electricity, coal and renewables. https://www.eia.gov/outlooks/steo/report/elec_coal_renew.php
- EIA press release, Sept. 9, 2026. https://www.eia.gov/pressroom/releases/press592.php
- EIA Electric Power Monthly, coal consumption table. https://www.eia.gov/electricity/monthly/epm_table_grapher.php?t=table_2_01_a
- IEA Coal Mid-Year Update 2026, demand chapter. https://www.iea.org/reports/coal-mid-year-update-2026/demand
- Global Energy Monitor, Boom and Bust Coal 2026 PDF. https://globalenergymonitor.org/sites/default/files/2026-05/GEM-Boom-and-Bust-Coal-2026.pdf
China
- Reuters, “China’s coal power on the rise again in 2026, reversing first-in-a-decade decline,” June 24, 2026. https://www.reuters.com/business/energy/chinas-coal-power-rise-again-2026-reversing-first-in-a-decade-decline-2026-06-24/
- Global Energy Monitor, “Built to peak: Coal power expansion runs out of room in China.” https://globalenergymonitor.org/research/built-peak-coal-power-expansion-runs-out-room-china
- CREA/GEM China coal power review H2 2025 PDF. https://energyandcleanair.org/wp/wp-content/uploads/2026/02/CREA_GEM_China_Coal-power_H2-2025.pdf
- CREA/GEM China coal power review H1 2026 PDF. https://energyandcleanair.org/wp/wp-content/uploads/2026/08/CREA_GEM_China_Coal-power-review_H1-2026.pdf
- Carbon Brief, “‘Rush’ for new coal in China hits record high in 2025.” https://www.carbonbrief.org/rush-for-new-coal-in-china-hits-record-high-in-2025-as-climate-deadline-looms/
- People’s Daily Online, “Solar overtakes coal as China’s top power source by installed capacity,” Sept. 22, 2026. http://en.people.cn/n3/2026/0922/c90000-20502488.html
- World Coal, “China’s coal-fired power generation declines for the first time since 2015.” https://www.worldcoal.com/coal/13022026/chinas-coal-fired-power-generation-declines-for-the-first-time-since-2015/
Additional context
- Energy News Beat site and channel style reference. https://energynewsbeat.co/