Crude fell about $19 a barrel in three sessions. Diesel fell by about the same amount in dollars, so the shortage premium barely moved. Stocks under 100 million barrels are a big reason food, freight and heating still feel expensive.
By Energy News Beat | As of November 9, 2026 CST
Published Nov. 9, 2026 | AAA national averages, Price as of 11/9/26 (captured about 7 a.m. CST; AAA updates daily) | Brent/WTI ~4:11 a.m. CT Nov. 9 (1011 GMT, CNBC) | An update to our Nov. 5 Strike or Deal / diesel crunch coverage | Not investment advice
Cheaper crude is not cheap diesel
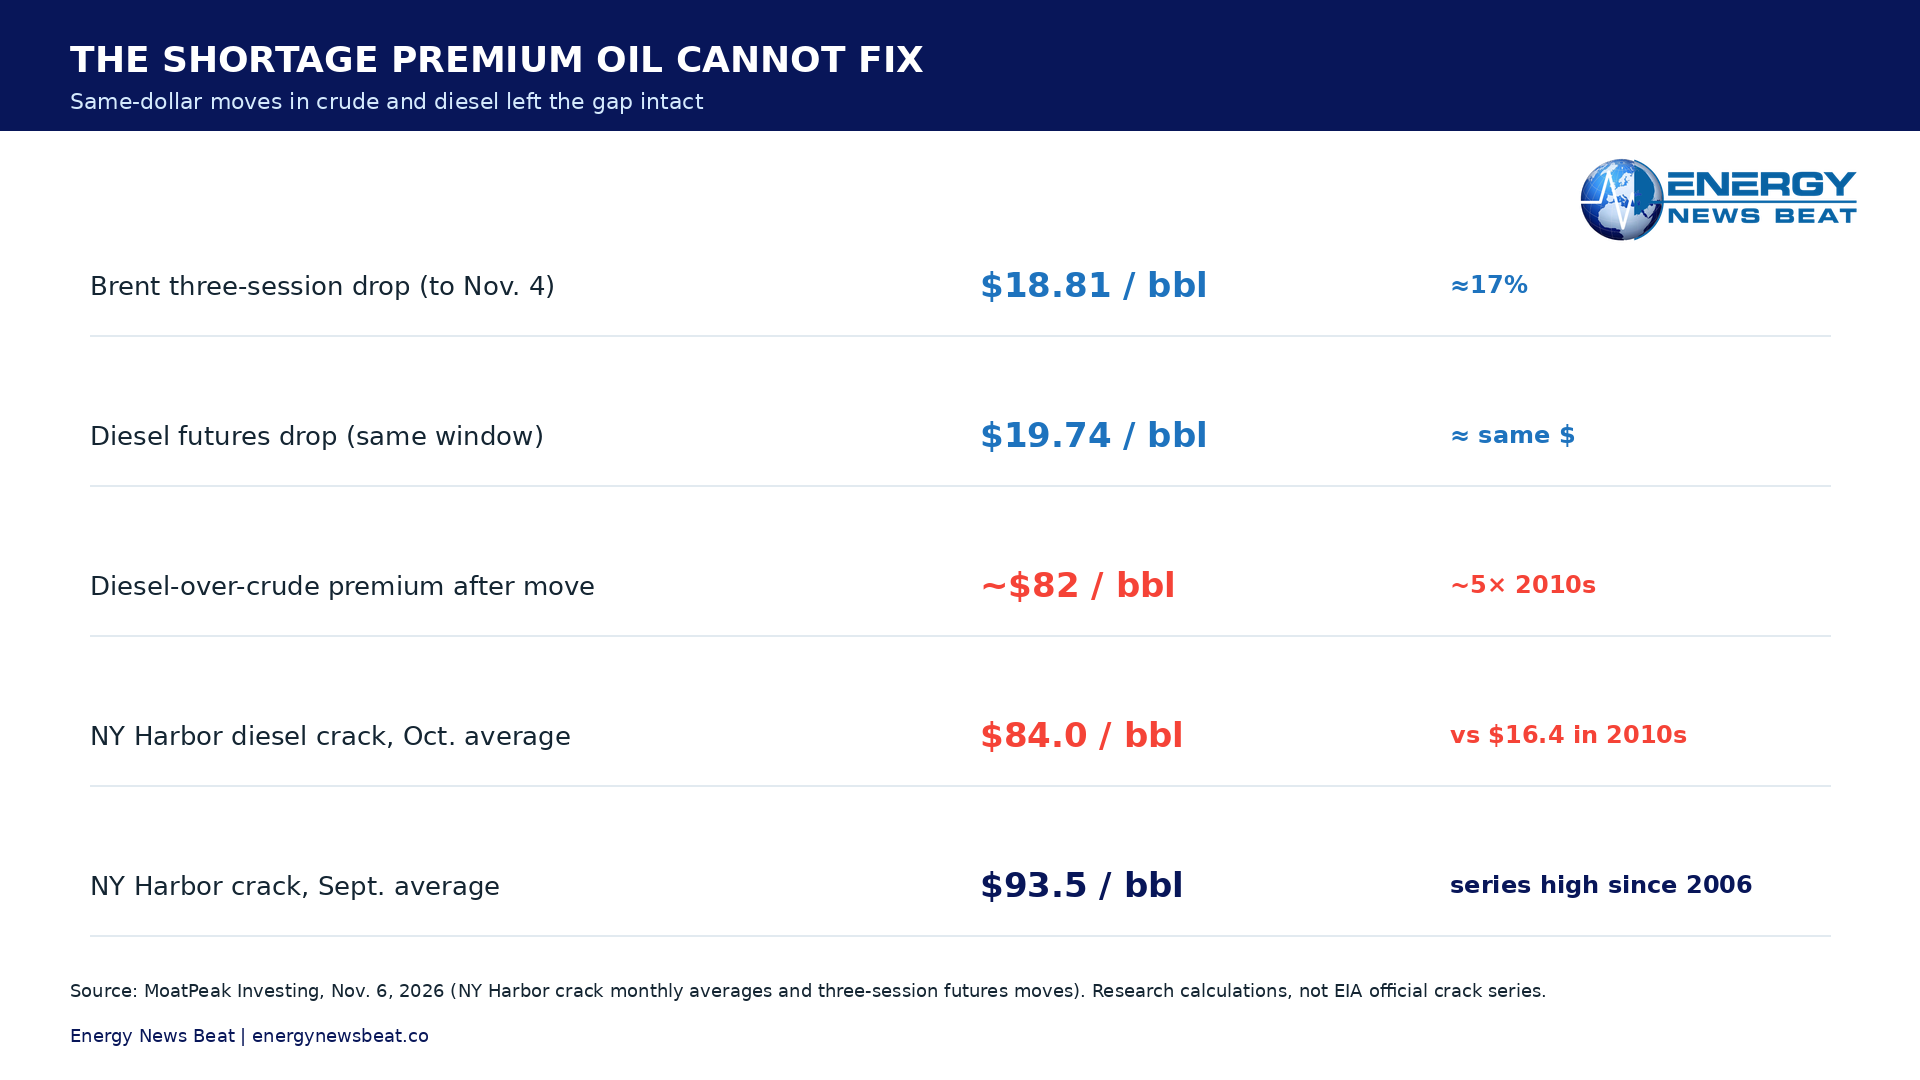
When oil prices crash, people expect the whole fuel aisle to follow. Last week’s move shows why that is only half true. Brent futures fell about $19 a barrel over three sessions through Nov. 4—MoatPeak Investing puts the drop at $18.81, or 17 percent—and diesel futures fell by almost the same amount in dollars, about $19.74. The premium diesel commands over crude barely budged, still near $82 a barrel, roughly five times its 2010s average. MoatPeak.
That premium is the part cheaper oil cannot fix. It is a shortage of refined distillate—diesel and heating oil—not a shortage of crude sitting in tanks. Gasoline is already easing at the pump. Diesel still shows up in groceries, freight invoices, farm fuel and Northeast heating bills long after the crude headline cools.
The tank is the problem
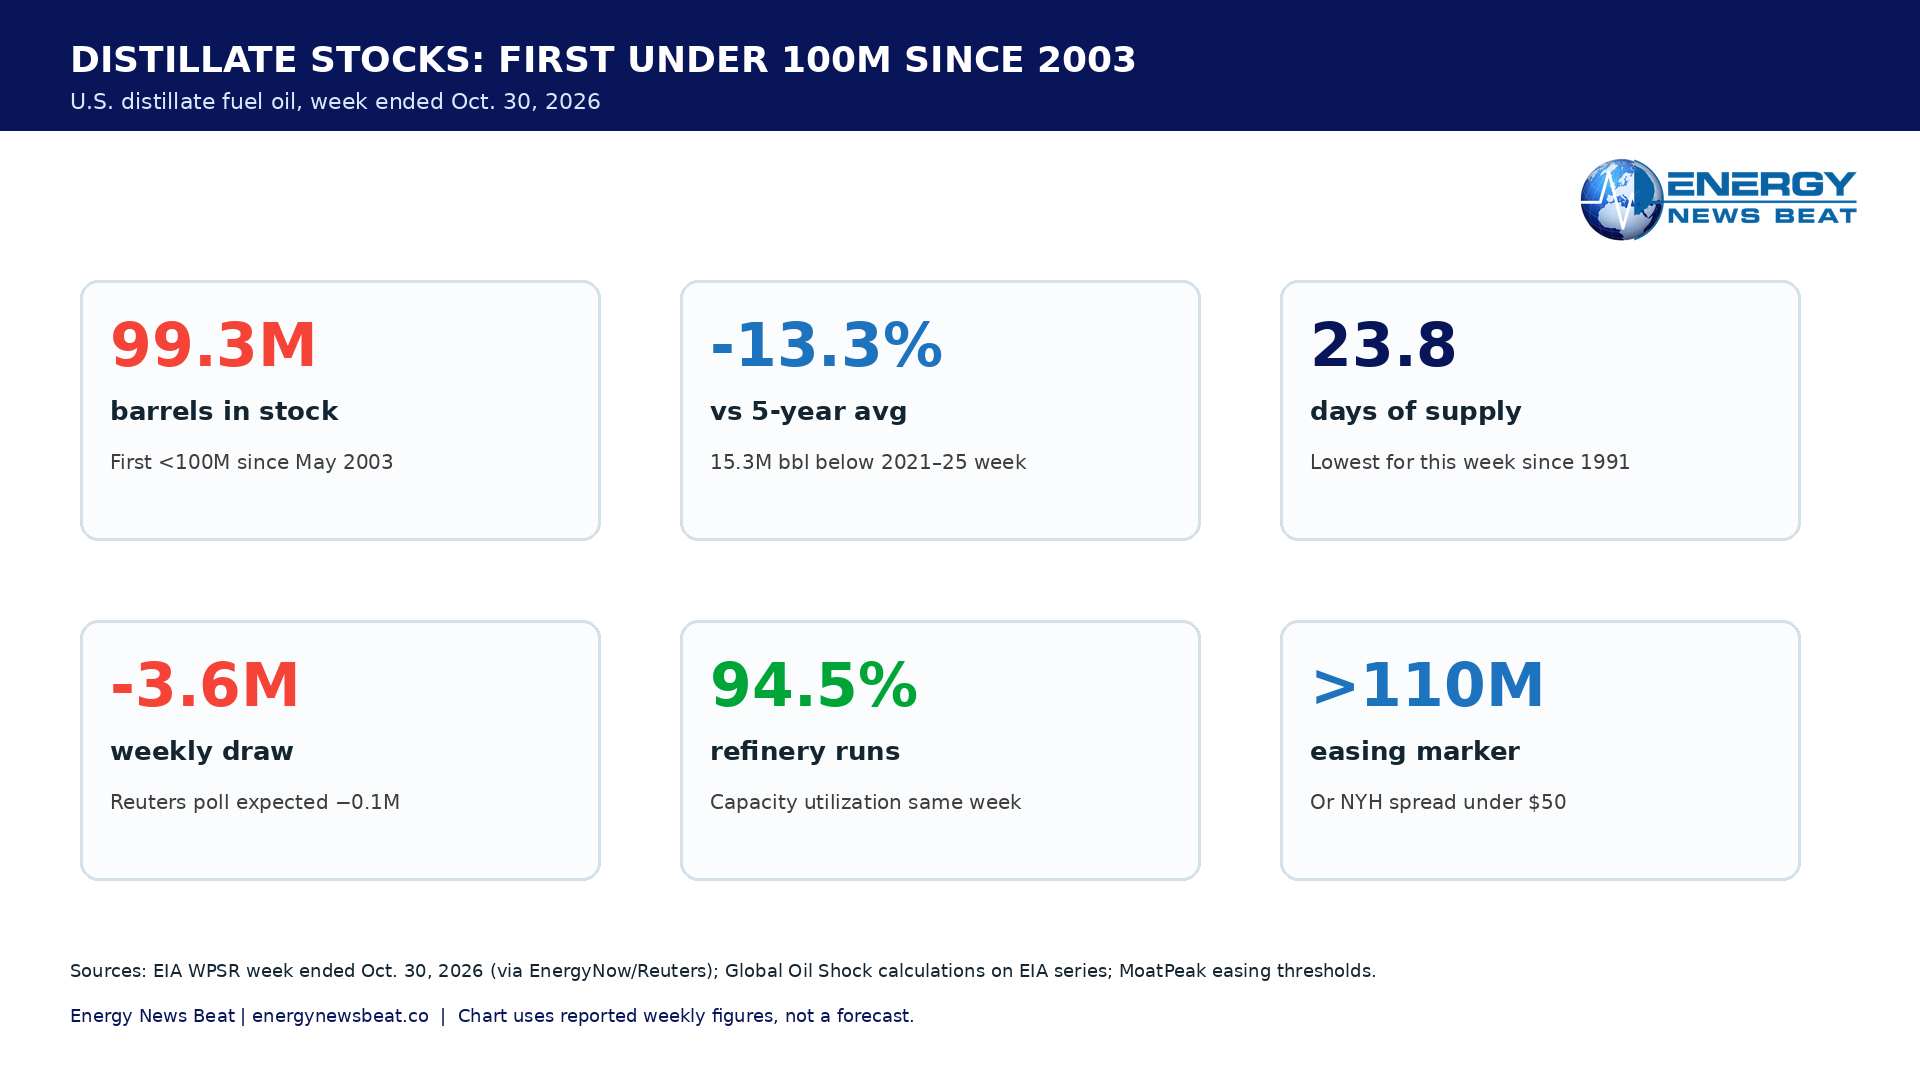
U.S. distillate stocks fell 3.6 million barrels in the week ended Oct. 30 to 99.3 million, the Energy Information Administration reported Nov. 4. That is the first reading under 100 million barrels since May 2003, per the EIA weekly distillate series, and analysts polled by Reuters had expected only a 100,000-barrel draw, per EnergyNow. EIA WPSR overview.
Against demand, those stocks cover 23.8 days of supply—the thinnest late-October cover since the demand series began in 1991, Global Oil Shock calculates from EIA data. Stocks sit 13.3 percent, or 15.3 million barrels, below the 2021–2025 average for the same week. Refineries ran at 94.5 percent of capacity the same week, so the shortfall is not for lack of effort at the plant gate.
MoatPeak’s easing markers are concrete: weekly distillate stocks back above 110 million barrels, or a New York Harbor diesel-crude spread sustained under $50. Neither has arrived. New York Harbor diesel cracks averaged $84 a barrel in October against $16.4 in the 2010s, and $93.5 in September—the highest monthly figure in MoatPeak’s series back to 2006. MoatPeak.
What the pump shows this morning
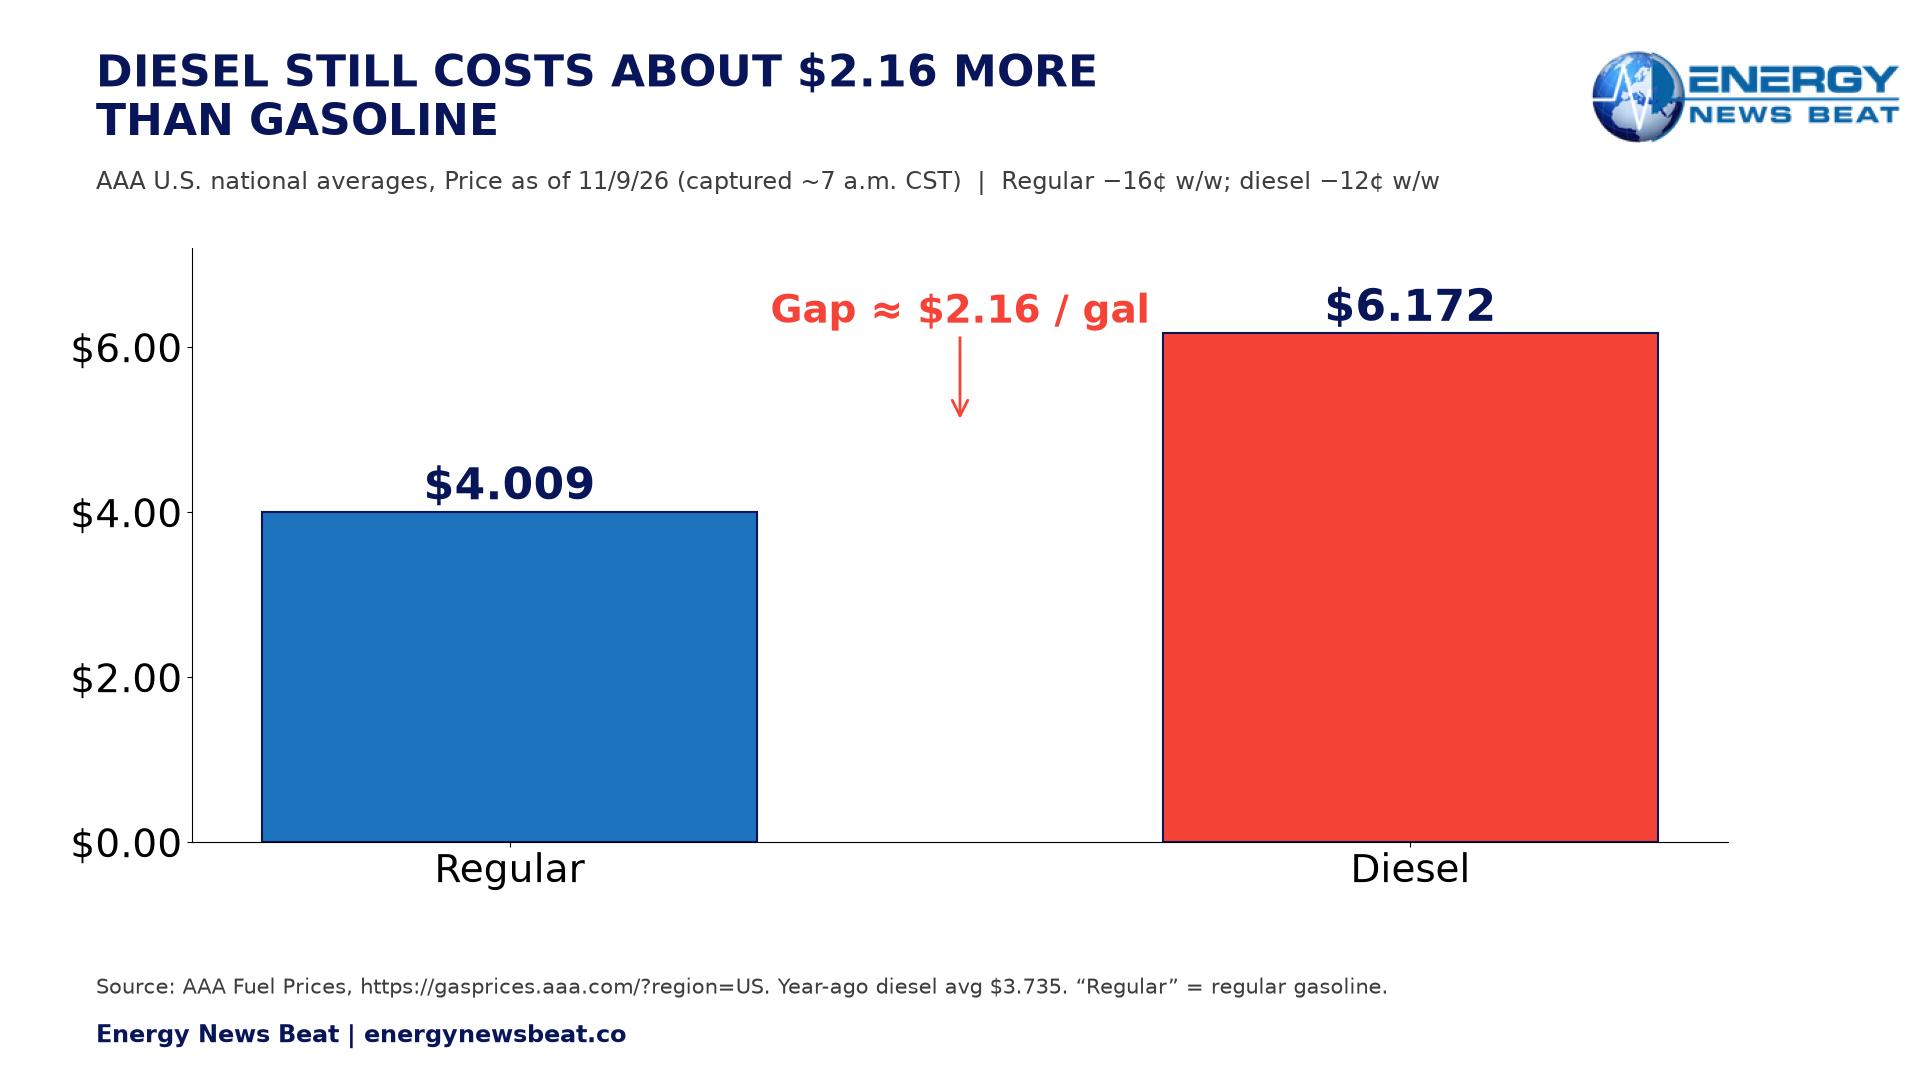
As of Nov. 9, AAA’s national average for regular gasoline is $4.009, down about 16 cents from a week ago. Diesel is $6.172, down about 12 cents from a week ago, versus 16 cents for regular. The diesel–gasoline gap is about $2.16 a gallon. Diesel remains about $2.44, or roughly 65 percent, above its year-ago AAA average of $3.735. AAA, Price as of 11/9/26 (captured about 7 a.m. CST; AAA updates daily).
GasBuddy’s Patrick De Haan said the national gasoline average fell below $4 a gallon for the first time since early August, with gasoline down in every state over the week, per WKYC. That is welcome for drivers. It does not refill distillate tanks.
Around 4:11 a.m. Central (1011 GMT) on Nov. 9, Brent was near $97.57 and WTI near $90.45, CNBC reported, after Brent’s roughly 16 percent weekly plunge—its steepest weekly drop since the start of the COVID-19 pandemic, per the same report. Crude is reacting to diplomacy talk and recovering Middle East flows. Diesel is still priced off a thin shelf.
Crude can go into surplus while diesel stays tight
JPMorgan said recovering Middle Eastern crude flows, rising production elsewhere and weak demand pushed the global oil market back into surplus—about 1.1 million barrels a day in September and 1.4 million in October, nearly matching last year’s average surplus of 1.3 million, Reuters via Investing.com. That is a crude-balance story. It does not automatically rebuild middle-distillate inventories.
Saxo Bank’s Ole Hansen sees Brent settling around $70–$90 even if West Asia tensions ease, because inventories still need to be rebuilt and pre-war $60–$70 pricing looks unlikely for now, per CNBC-TV18 on Nov. 8. Crude can cool and still leave diesel expensive if refiners cannot make enough of it, or if overseas product exports stay constrained.
EIA’s September Short-Term Energy Outlook forecast U.S. distillate inventories would fall below 100 million barrels and remain below the 2021–2025 five-year low through the end of 2026 and most of 2027—language GoldSquawk correctly flagged and that we verified on the September STEO PDF. The newer October STEO (forecast completed Oct. 1; next release Nov. 10) still expects U.S. distillate inventories to stay below the 2021–2025 average through the forecast horizon, with East Coast stocks 20–30 percent below their seasonal average this winter, and retail diesel above $6 in October before gradually easing. Multi-year tightness remains the official baseline, even as the October wording softens the “five-year low” phrasing.
Heating oil, a tiny reserve release, and one refinery hiccup
Residential heating oil averaged $6.138 a gallon (EIA’s U.S. average of surveyed states, excluding taxes) as of Nov. 2, up $2.506 from a year earlier—about 69 percent, by EIA’s Heating Oil and Propane Update. EIA. That is the Northeast kitchen-table number that follows the same distillate shortage as truck diesel.
DOE awarded contracts on Nov. 4 to exchange 300,000 barrels from the Northeast Home Heating Oil Reserve, drawn from Boston and New Haven, with deliveries scheduled by Nov. 6 and barrels to be returned with a premium. That followed an Oct. 21 request for up to 315,000 barrels. DOE; Oct. 21 RFP. Against a 3.6-million-barrel weekly draw, that is a policy signal measured in hours of national demand, not a refill of the national tank.
Supply fragility shows up in ordinary outages too. Delek reported an equipment malfunction on Nov. 6 at the fluid catalytic cracking unit of its Big Spring, Texas, refinery (about 73,000 barrels a day of capacity), with FCC operations adjusted to minimize carbon-monoxide and sulfur-dioxide emissions, per a Reuters summary of a Texas Commission on Environmental Quality filing. One midsize FCCU event is not a national shortage by itself, and no throughput loss has been reported. In a 99-million-barrel tank, any lost output would matter more than it would in a comfortable year.
What it means for consumers
Diesel is how America moves food, parcels, building materials and harvest equipment. When it stays near $6 while gasoline slips to about $4, households feel the diesel bill indirectly—in grocery markups, delivery fees and the cost of everything that rode a truck. Farmers and owner-operators feel it directly in the tank.
Northeast families on heating oil enter winter with national distillate stocks under 100 million barrels and East Coast inventories still deeply below normal in EIA’s October outlook. Locking a budget or a fixed price where a dealer offers one is a household decision, not a market forecast—but the inventory math does not promise a quick winter collapse in heating-oil bills.
Freight fuel surcharges usually lag. Most U.S. trucking fuel surcharges are indexed to the weekly government diesel price, which is still far above a year ago even after last week’s crude crash, MoatPeak notes. Cheaper Brent today does not erase last month’s diesel invoice overnight.
What investors should watch
Wide diesel cracks mean fat refining margins while the shortage lasts. That is an earnings tailwind for complex refiners that can maximize distillate yield—until inventories rebuild, maintenance catches up, or product imports surge. Falling crude with a steady diesel premium leaves refiners’ diesel margins largely intact; fleets get the crude-linked part of the relief, but not the shortage premium.
Watch the two MoatPeak markers—stocks above 110 million barrels or NY Harbor spreads under $50—alongside EIA’s weekly stock report (this week Thursday, Nov. 12, delayed by Veterans Day) and East Coast distillate levels. EIA WPSR schedule. Watch whether freight surcharges lag the pump; equity stories that price instant diesel relief into transports can get ahead of the surcharge math.
This is not a stock tip. Direct retail exposure to “diesel shortage” is mostly through listed refiners, midstream logistics and freight names already in public markets; contract risk, utilization and maintenance schedules matter more than a headline crack number. None of this is investment advice.
Caveats and fair criticism
Our reading could be too harsh. Futures already price some diesel relief into December, MoatPeak notes, and demand destruction at $6-plus diesel can rebuild stocks faster than any single refinery. A durable reopening of Middle East product exports would do more than any domestic reserve exchange. The October STEO is already softer on the “five-year low” language than September’s, and EIA’s next STEO is due Nov. 10.
We did not use widely circulated JPMorgan 2027 Brent scenario figures because we could not verify them against the bank’s original note. On Nov. 8 the Houthis claimed strikes on Saudi targets including Aramco facilities at Abqaiq; Saudi Arabia’s energy ministry acknowledged only an attempted attack that caused minor damage to an Aramco administrative building in Riyadh. AFP; CNBC. We found no confirmed damage at Abqaiq and treat no Saudi supply loss as established.
MoatPeak’s $82 premium and $84 October crack are research calculations on futures and NY Harbor differentials, not EIA official series. AAA and GasBuddy are parallel retail surveys with different methods and timestamps. National stock totals can hide worse regional tightness, especially in New England heating oil.
Stu’s Take
Cheaper crude is good news. It is not cheap diesel. Brent fell roughly $19 over three sessions while the diesel-over-crude premium stayed near $82—about five times the 2010s norm (MoatPeak). Distillate stocks are 99.3 million barrels, first under 100 million since 2003, 13.3% below the five-year average and 23.8 days of cover (EIA/EnergyNow; GOS).
AAA has regular at $4.009 and diesel at $6.172, a $2.16 gap (AAA). Heating oil was $6.138 as of Nov. 2, up about 69% year over year (EIA). JPMorgan sees crude back in surplus; that does not refill middle-distillate tanks (Reuters). EIA’s September STEO had stocks below the five-year low through most of 2027; October still keeps inventories below the five-year average through the forecast (September STEO; October STEO).
Watch MoatPeak’s markers: stocks above 110 million barrels, or the NY Harbor diesel spread under $50. Until then, truckers, farmers and oil-heat families should budget for diesel pain even when the oil ticker looks friendly.
Appendix A | Linked source list (access Nov. 9, 2026 CST)
Selected excerpts are short evidence pointers, not full reproductions. An access gap is not proof a document does not exist.
01. MoatPeak Investing, Cheaper Crude Leaves Diesel’s Shortage Premium Intact, Nov. 6, 2026
Selected excerpt: “Brent crude futures fell $18.81 a barrel over the three sessions to 4 November… Diesel futures fell by almost the same amount in dollars, $19.74… premium… about $82”
Core analytical frame: unchanged shortage premium, $84 Oct / $16.4 2010s NYH crack, easing thresholds 110M bbl or <$50 spread; also trucking-surcharge indexing. Research blog, not EIA.
https://read.moatpeak.com/p/cheaper-crude-leaves-diesels-shortage
02. Reuters via EnergyNow, US Crude Stocks, Gasoline and Distillate Inventories Fall – EIA, Nov. 4, 2026
Selected excerpt: “Distillate stockpiles… fell by 3.6 million barrels… to 99.3 million barrels, versus expectations for a 100,000-barrel drop”
Confirms EIA weekly print and Reuters poll surprise.
https://energynow.com/2026/11/us-crude-stocks-gasoline-and-distillate-inventories-fall-eia/
03. Global Oil Shock, US oil inventories page, updated Nov. 5, 2026
Selected excerpt: “99.3 million barrels… 13.3% below… 23.8 days… lowest for this time of year since 1991”
GOS calculations on EIA WDISTUS1 / days-of-supply series; seasonal lows are GOS/EIA-history claims.
https://globaloilshock.com/en/data/us-oil-inventories/
04. AAA Fuel Prices, national averages, Price as of 11/9/26 (captured about 7 a.m. CST)
Selected excerpt: “Regular $4.0093; Diesel $6.1723; Week Ago Regular $4.1694 / Diesel $6.2921; Year Ago Diesel $3.7345”
Live national averages; AAA publishes no intraday timestamp and updates daily.
https://gasprices.aaa.com/?region=US
05. CNBC, Oil falls as Trump signals restraint on Iran…, updated Nov. 9, 2026
Selected excerpt: “Brent… $97.57… WTI… $90.45… plunged 16% last week”
As-of ~1011 GMT Nov. 9 (intraday, not settlements); also carries JPMorgan surplus and Houthi claim lines.
https://www.cnbc.com/2026/11/09/oil-falls-as-trump-says-new-iran-attacks-unlikely.html
06. Reuters via Investing.com, As high oil prices curb demand, fresh signs of glut appear, Nov. 5–6, 2026
Selected excerpt: “surplus of 1.1 million barrels per day in September, widening to 1.4 million bpd in October”
JPMorgan crude-balance estimate; not a distillate inventory forecast.
07. CNBC-TV18, Brent crude may find support at $70-$90…, Nov. 8, 2026
Selected excerpt: “Hansen expects Brent crude to settle in the $70-$90 per barrel range”
Ole Hansen / Saxo outlook; not in the Nov. 9 CNBC.com oil wrap.
08. EIA Short-Term Energy Outlook, September 2026 PDF
Selected excerpt: “remain below the five-year (2021–2025) low through the end of 2026 and most of 2027”
Primary PDF verified; overview bullet says “much of 2027.”
https://www.eia.gov/outlooks/steo/archives/Sep26.pdf
09. EIA Short-Term Energy Outlook, October 2026 archive PDF (Oct26.pdf)
Selected excerpt: “U.S. distillate fuel inventories to remain below the 2021–2025 average throughout the forecast period”
Pinned October archive URL (live as of this draft; next monthly STEO release is Nov. 10).
https://www.eia.gov/outlooks/steo/archives/Oct26.pdf
10. EIA STEO petroleum products page, Release Date Oct. 6, 2026 (Oct. 6 release text, replaced Nov. 10)
Selected excerpt: “East Coast… remain between 20% and 30% below the five-year average through the upcoming winter”
HTML companion to October STEO; page text changes with each monthly release.
https://www.eia.gov/outlooks/steo/report/petro_prod.php
11. GoldSquawk Oil Report, Diesel tightness…, Nov. 6, 2026
Selected excerpt: “EIA had already signalled… remain below the 2021–2025 five-year low through end-2026 and most of 2027”
Secondary pointer to September STEO; primary PDF checked.
12. EIA Heating Oil and Propane Update, prices as of 11/02/26
Selected excerpt: “U.S. Average residential heating oil $6.138; change from year ago +2.506”
Excluding taxes. Implies ~69% y/y on $3.632 year-ago level (ENB calc).
https://www.eia.gov/petroleum/heatingoilpropane/
13. DOE, Energy Department Awards Contracts from Northeast Home Heating Oil Reserve, Nov. 4, 2026
Selected excerpt: “contract awards for the exchange of 300,000 barrels… Boston… and New Haven… completed by November 6, 2026”
Award superseded the Oct. 21 RFP ceiling of up to 315,000 barrels.
14. DOE, Energy Department Authorizes Exchange from Northeast Home Heating Oil Reserve, Oct. 21, 2026
Selected excerpt: “exchange of up to 315,000 barrels… completed by November 13, 2026”
RFP ceiling and earlier delivery window; replaced by Nov. 4 awards.
15. TradingView reprint of Reuters headline on Delek Big Spring FCCU
Selected excerpt: “Delek Big Spring, Texas Refinery Reports Equipment Malfunction at FCCU”
Headline page thin; operational details from Reuters brief.
16. Reuters summary via Boursorama, Nov. 8–9, 2026
Selected excerpt: “equipment malfunction… FCC… Nov. 6… capacity 73,000 b/d… operations adjusted to minimize CO and SO2”
Machine-translated Reuters brief, timestamp Nov. 8 CST; cites TCEQ filing. No throughput loss reported.
17. EIA Weekly Petroleum Status Report landing
Data pointer: EIA weekly data hub; week ended Oct. 30 figures confirmed in WPSR Table 1 (overview.pdf) and series WDISTUS1
Official weekly stocks home and schedule.
https://www.eia.gov/petroleum/supply/weekly/
18. EIA WPSR overview tables PDF
Data pointer: Table 1 distillate stocks 99.3 million barrels; Table 2 utilization 94.5%
Primary weekly tables for week ended Oct. 30, 2026.
https://ir.eia.gov/wpsr/overview.pdf
19. EIA Weekly U.S. Ending Stocks of Distillate Fuel Oil (WDISTUS1)
Data pointer: Last earlier sub-100M week: May 9, 2003 (99,878 kb); Oct 30, 2026: 99,259 kb
Primary series for “first under 100M since May 2003.”
https://www.eia.gov/dnav/pet/hist/LeafHandler.ashx?n=PET&s=WDISTUS1&f=W
20. WKYC / GasBuddy, Patrick De Haan commentary, Nov. 9, 2026
Selected excerpt: “national average dropped below $4 per gallon for the first time since early August”
De Haan quote and sub-$4 claim via WKYC; GasBuddy national diesel about $6.18 per WJON, Nov. 9 (https://wjon.com/gas-prices-drop-nationally/).
21. AFP, Yemen’s Houthis claim attack on Riyadh financial district…, Nov. 8, 2026
Selected excerpt: “energy ministry… attempted attack… minor damage to the building”
Saudi ministry confirmation limited to Riyadh administrative building; Houthi list included Abqaiq.
22. EIA Weekly Petroleum Status Report release schedule
Data pointer: Week ending Nov. 6 data: Thursday, Nov. 12, 2026, 12:00 p.m. ET (11:00 a.m. CST)
Veterans Day delay.
https://www.eia.gov/petroleum/supply/weekly/schedule.php
Appendix B | Key data tables (as-of dates labeled)
B1. AAA national retail averages
| Snapshot | Regular $/gal | Diesel $/gal | Notes |
| Current (Price as of 11/9/26; captured ~7 a.m. CST) | $4.0093 | $6.1723 | AAA live page |
| Yesterday | $4.0203 | $6.1929 | AAA |
| Week ago | $4.1694 | $6.2921 | Regular −~16¢; diesel −~12¢ |
| Month ago | $4.3718 | $6.2785 | AAA |
| Year ago | $3.0699 | $3.7345 | AAA |
| Diesel–regular gap (current) | — | $2.163 | ENB calc: 6.1723−4.0093 |
B2. Distillate inventories and utilization
| Metric | Value | As-of / source |
| U.S. distillate stocks | 99.3 million bbl | Week ended Oct. 30, 2026; EIA via EnergyNow / WPSR overview |
| Weekly change | −3.6 million bbl | EIA; Reuters poll expected −0.1M |
| vs 5-year avg (same week) | −13.3% / −15.3M bbl | GOS calc on EIA; avg 114.5M |
| Days of supply | 23.8 days | EIA via GOS; lowest for week since 1991 |
| First <100M since | May 2003 | EIA WDISTUS1 / MoatPeak |
| Refinery utilization | 94.5% | EIA week ended Oct. 30 |
| East Coast stocks (context) | 22.6M bbl late Oct (MoatPeak) | vs 58.6M late Oct 2015 (MoatPeak) |
| MoatPeak easing: stocks | >110 million bbl | Still below late-Oct 2023–25 levels |
| MoatPeak easing: NYH spread | <$50 / bbl sustained | Research threshold |
B3. Cracks, crude, heating oil, reserve
| Metric | Value | Source / date |
| Brent 3-session drop to Nov. 4 | $18.81 / bbl (−17%) | MoatPeak |
| Diesel futures drop same window | $19.74 / bbl | MoatPeak |
| Diesel-over-crude premium after | ~$82 / bbl | MoatPeak |
| NYH diesel crack Oct avg | $84.0 / bbl | MoatPeak (vs $16.4 in 2010s) |
| NYH diesel crack Sept avg | $93.5 / bbl | MoatPeak (series high since 2006) |
| Brent ~4:11 a.m. CT Nov. 9 | $97.57 | CNBC (1011 GMT, intraday) |
| WTI same timestamp | $90.45 | CNBC |
| Brent weekly change | ≈ −16% | CNBC (steepest since COVID start) |
| JPMorgan surplus Sept / Oct | 1.1 / 1.4 mb/d | Reuters via Investing.com |
| Saxo Hansen Brent settling zone | $70–$90 | CNBC-TV18, Nov. 8, 2026 |
| Residential heating oil US avg | $6.138 / gal (excl. taxes) | EIA as of 11/02/26 |
| Heating oil y/y change | +$2.506 (~69%) | EIA; ENB % calc |
| NEHHOR exchange awarded | 300,000 bbl (RFP ceiling 315,000) | DOE Nov. 4 / Oct. 21, 2026 |
| Delek Big Spring FCCU event | Malfunction Nov. 6; 73 kb/d plant | Reuters brief / TCEQ cite; no lost output reported |
Appendix C | Background and prior ENB context
This piece updates the diesel/consumer thread from ENB’s Nov. 5 coverage: “Strike or Deal? What the U.S. Build-Up and Six Chokepoints Are Telling Oil and Diesel Markets” and “How Long Until Diesel Relief? Not This Winter, and Probably Not Before the Second Half of 2027.” Those reports stressed multi-year distillate tightness; this update asks why a ~$19 crude crash did not erase the diesel shortage premium.
Angle for readers: gasoline can ease with crude while diesel, freight and heating oil stay expensive until inventories rebuild. Investor section focuses on refining margins and lagging freight surcharges without unsupported ticker recommendations.
Appendix D | Methodology and arithmetic
AAA prices: national averages from gasprices.aaa.com, Price as of 11/9/26, captured about 7 a.m. CST Nov. 9, 2026 (AAA updates daily). Weekly drop in regular ≈ $4.1694 − $4.0093 = $0.1601 (~16 cents). Weekly drop in diesel ≈ $6.2921 − $6.1723 = $0.1198 (~12 cents). Diesel–regular gap = $6.1723 − $4.0093 = $2.163 (~$2.16). Diesel y/y ≈ $6.1723 − $3.7345 = $2.4378 (~65%).
Heating oil y/y percent: $2.506 / ($6.138 − $2.506) = $2.506 / $3.632 ≈ 69.0%. EIA prices exclude taxes.
MoatPeak three-session crude/diesel moves and NY Harbor crack monthly averages are MoatPeak research figures; we did not independently rebuild the crack series from raw NY Harbor spot prints for this draft.
GOS 13.3% / 23.8 days / seasonal lows are GOS calculations on EIA weekly series; EnergyNow and WPSR overview confirm the 99.3M and −3.6M EIA prints. “First under 100M since May 2003” follows EIA WDISTUS1 (last earlier sub-100M week May 9, 2003).
EIA STEO: September PDF primary language on stocks below the 2021–2025 five-year low through end-2026 and most of 2027 verified. October STEO archive (Oct26.pdf; next release Nov. 10) expects inventories below the five-year average through the forecast and East Coast stocks 20–30% below average this winter—softening the “five-year low” phrasing while keeping multi-year tightness.
Reserve arithmetic: awarded 300,000 / 3,600,000 weekly draw ≈ 8.3%; 300,000 / ~4.2–4.4 million b/d distillate product supplied ≈ 1.6–1.7 hours. Illustrative ENB arithmetic.
GasBuddy sub-$4 claim and De Haan quote via WKYC Nov. 9 local report.
All times Central unless a source states otherwise; CNBC’s 1011 GMT = 4:11 a.m. CT on Nov. 9, 2026 (CST, UTC−6). Next WPSR: Thursday, Nov. 12, 2026, 11:00 a.m. CST (Veterans Day delay).
Appendix E | Verification limits and omissions
Widely circulated JPMorgan 2027 Brent scenario figures were seen only in secondary summaries (BigGo, GuruFocus, Bitget), which disagree on the baseline ($63 vs $64); original note and date not verified — omitted from body claims.
Houthi claims of strikes including Abqaiq: Saudi energy ministry via AFP confirmed only minor damage to an Aramco administrative building in Riyadh; no confirmed Abqaiq damage or Saudi supply loss used as an input.
Delek Big Spring FCCU item rests on a machine-translated Reuters brief citing a TCEQ filing; no throughput loss reported.
MoatPeak NYH crack averages and three-session futures moves remain attributed as MoatPeak research calculations.
AAA and Brent/WTI figures are timestamped; AAA updates daily and CNBC prices at 1011 GMT are intraday, not settlements.